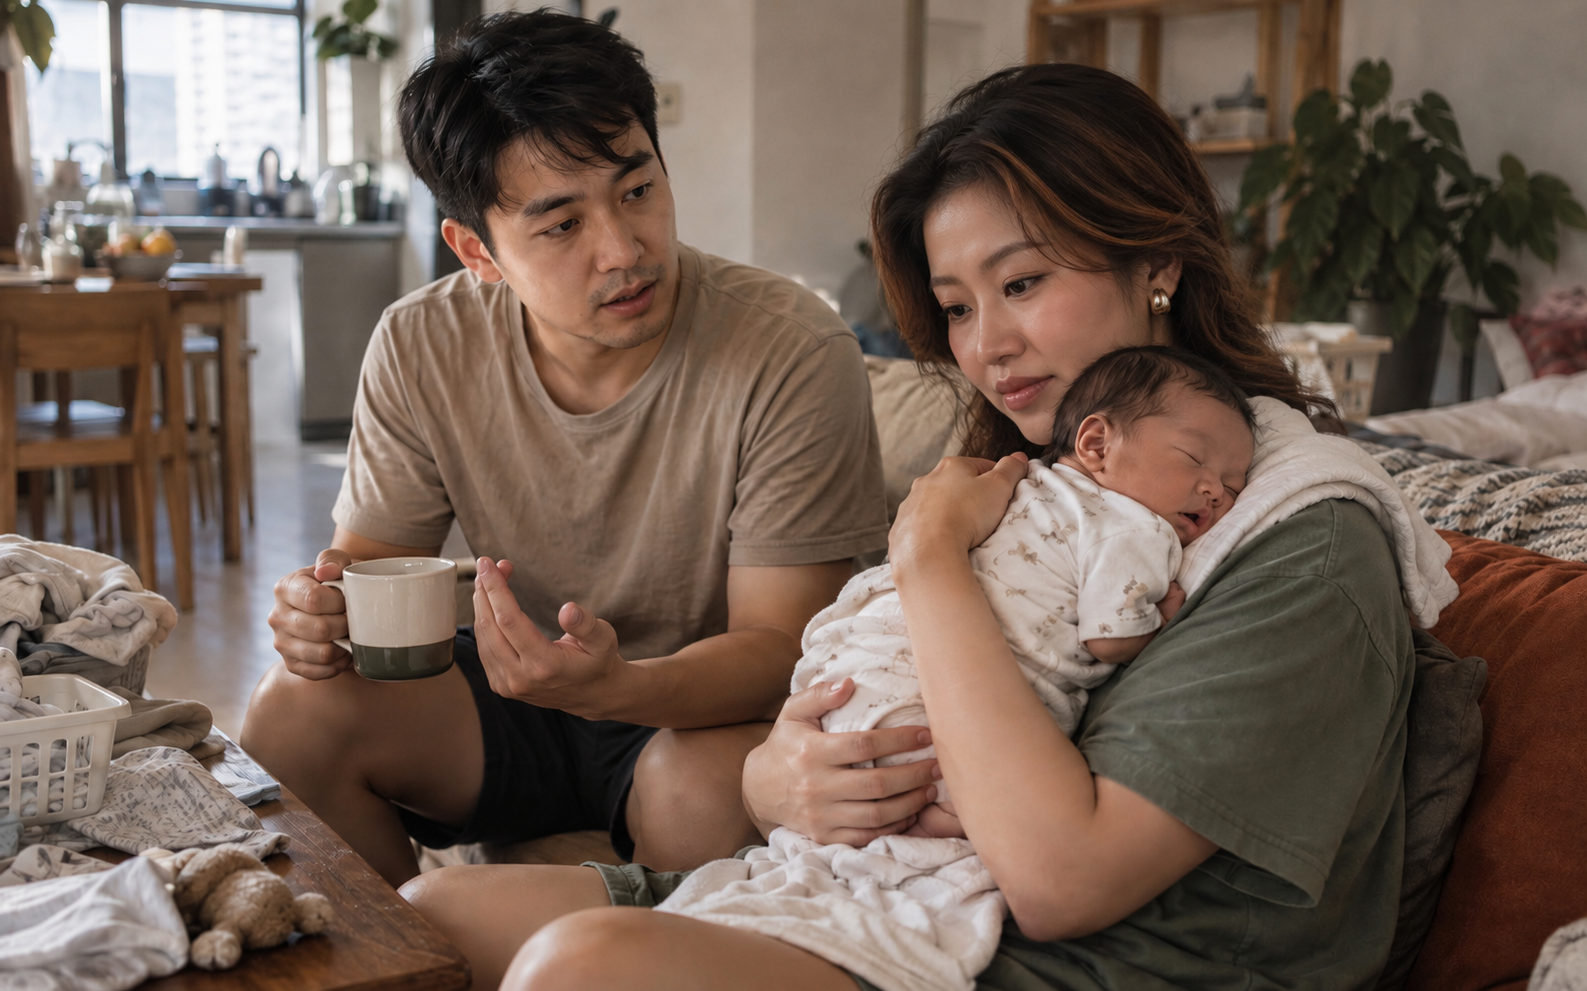
01A first child, or a second, and the household now depends on 1 or 2 incomes
Protection & Planning
Most of us have one quiet question:If I were no longer here, would the people I love be taken care of?It’s a question worth planning for.
Something changes, and a question that was easy to postpone stops being easy to postpone.
This page is about the 4 ideas that cover most of family protection, what each one is for, and how the conversation goes. You do not need all four, and you may already hold more than you remember.
If you would rather understand a policy you already have, Existing Policy Support is the better place to start.
What it actually means
Each one explained in a sentence you will not need translated. Most families use 2 or 3 of them, not all 4.
A sum paid to the people you name if you die. It replaces what your household would lose, the income and the mortgage, for as long as they would have needed it.
Pays out if illness or injury means you can no longer work at all. It often matters more than people expect: the household keeps its costs and loses its earner.
A lump sum on diagnosis of a defined serious condition. Not the same as medical cover: this money is yours for anything, including the months you cannot work.
Who receives the money, and how quickly. The part most often left incomplete, and the part that decides whether a payout helps in the first month or the first year.
How the conversation goes
Who depends on you, what they depend on you for, and what would still need paying if your income stopped. That is the whole first conversation.
Including cover from an employer or a policy bought elsewhere. Often there is more in place than people remember, and the gap is smaller than they feared.
What each one does, what it costs, and what it does not do. If 2 options are close, we will say so rather than steer you.
Including deciding not to. If what you have is already reasonable, we would rather tell you that and stay in touch.
“The families who are glad they did this are rarely the ones who bought the most. They are the ones who understood what they bought.”
There is no universal number. A common starting point is what your household would need to stay steady for the years your dependants still rely on you, covering outstanding loans, living costs and education, less what is already in place. We work it through with you rather than quoting a rule of thumb.
It may be, and we will tell you if it is. Employer cover is worth understanding on 2 points: how much it actually pays, and whether it continues if you change jobs or stop working. Those 2 answers usually settle the question.
Not necessarily, though it does change what is available and what it costs. It is better to ask than to assume, and if the honest answer is that a policy no longer makes sense for you, we will say so.
Most arrangements can be reviewed and adjusted as your life changes. That is the point of having an advisor rather than a policy document: someone reviews it with you when something changes.
Next step
No forms, no products in the first meeting. Just what your family would need, and what you already have in place.
Most conversations with us don’t end in a decision, and that’s completely fine.