01Whether EPF alone will be enough, and what “enough” even means
Protection & Planning
Retirement planning is less about a number than about a series of decisions you could explain, in your own words, to your own family.
They arrive with a feeling that they should have one.
Underneath that feeling there are usually a few specific worries. This page sets out the 4 components of a retirement picture, and how we work through them with you.
Most Malaysian households already have at least two of the four in place.
What it actually means
4 components, and most Malaysian households already have at least two of them.
The foundation for most people. Worth knowing what it is projected to provide monthly rather than as a total. The monthly figure is the one that tells you something.
What you set aside beyond EPF, and how it is invested. Time horizon matters more than product selection at almost every stage of this.
Arrangements that pay out over time rather than as a lump sum. Their value is predictability, their cost is flexibility, and the trade depends on what else you hold.
Medical cover in later life, and cover that protects the plan if you cannot work to the end of it. A plan assuming uninterrupted earnings carries one large assumption.
How the conversation goes
What you want the years after work to look like, in ordinary terms. The number follows from that, rather than the other way round.
EPF, savings, property, existing policies. Most people are further along than they think, and seeing it in one place is often the most useful part.
Including when the honest answer is that the target needs adjusting rather than the contributions. Not every gap closes, and pretending otherwise helps nobody.
A plan set once and never reviewed is a document, not a plan. Income changes, families change, and the plan should move with them.
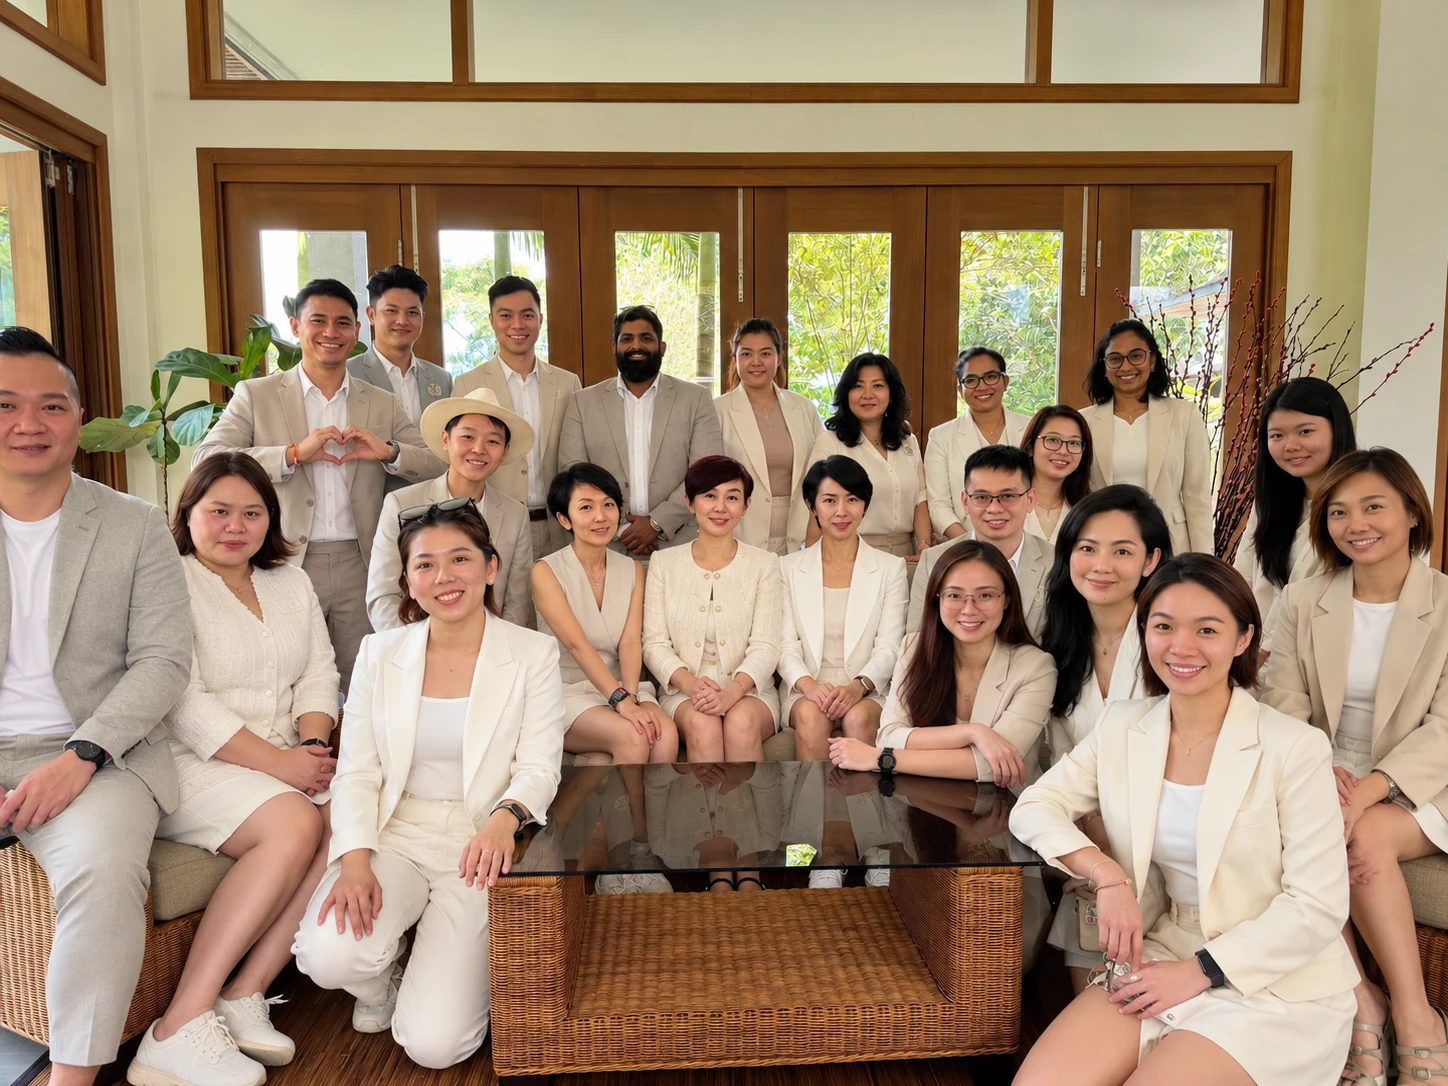
“The best plans we see are not the most sophisticated ones. They are the ones the client can still explain, 5 years later, without looking anything up.”
Earlier helps, because time does more work than contribution size. But starting later with a realistic target beats not starting because the ideal moment has passed. Neither answer requires you to decide anything today.
For some households, close to it. For many, it covers the essentials and not much beyond them. The way to know is to look at your own projected monthly figure against the life you have in mind, which is a short conversation.
Not to have the conversation. And if a long commitment does not suit your circumstances, we would rather find that out with you than sell around it.
Next step
EPF, savings, property, policies. Seeing it together is usually the point at which planning stops feeling abstract.
Most conversations with us don’t end in a decision, and that’s completely fine.